Most people have encountered Confirmation of Payee (CoP) without giving it much thought. You set up a payment in your banking app, enter the recipient’s name and account details, and your bank confirms whether they match. It takes seconds, and you move on.
For businesses, however, CoP is more significant because they sit on both sides of the check. Businesses use it when paying suppliers and staff, while their customers use it when making payments to them. Getting the first right helps protect outgoing payments from fraud. Getting the second right, helps protect revenue from payments that never happen.
What is Confirmation of Payee?
Confirmation of Payee is a real-time check that confirms whether the name entered for a payment matches the name held against the receiving bank account. It applies to push payments such as Faster Payments and CHAPS and is separate from the checks used for Direct Debits.
CoP was introduced to address a fundamental weakness in traditional bank transfers. Sort codes and account numbers determine where money goes, but historically there was no equivalent check that the recipient’s name matched the account. This created an opportunity for invoice redirection and other payment fraud.
Following the Payment Systems Regulator’s Specific Direction 17, around 400 UK firms were required to implement CoP by 31 October 2024. Coverage now extends to more than 99% of Faster Payments and CHAPS.
Understanding the Responses
A CoP check generally produces one of four outcomes:
- Match: The name supplied matches the account and the payment can proceed.
- Close match: The name is similar but not identical. This can be legitimate, for example because of an abbreviation, trading name or missing “Ltd”, but it requires judgement.
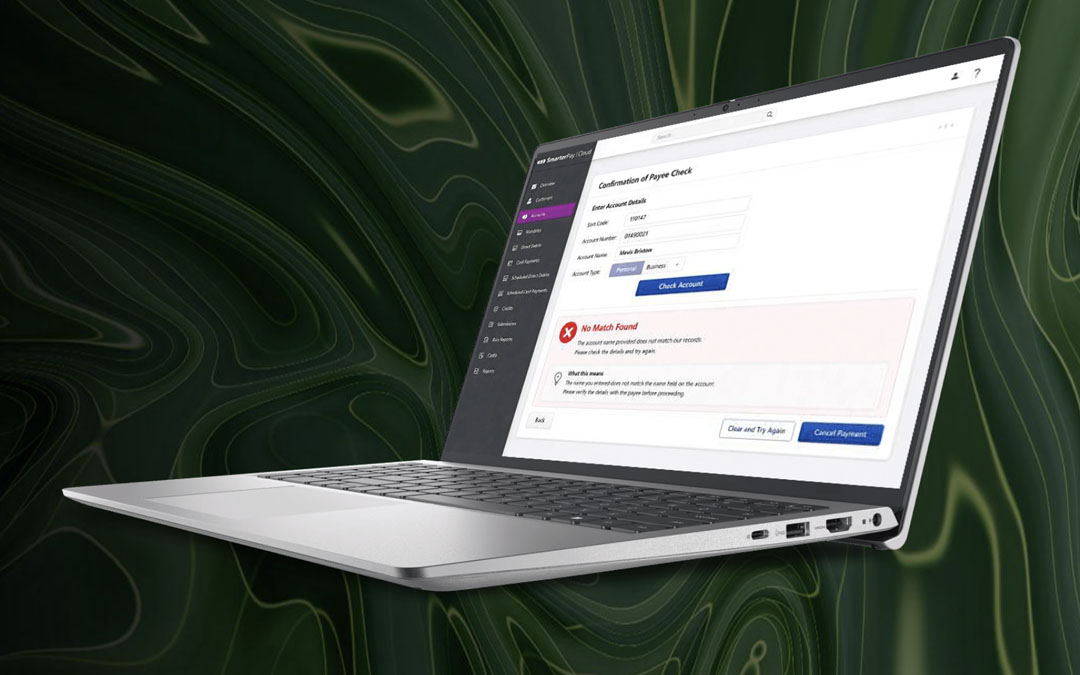
- No match: The name does not correspond with the account. The payment should normally be stopped and the details independently verified.
- Unavailable: The check could not be completed. This is not the same as a successful check and should not automatically be treated as a pass.
There can also be an account type mismatch, where the details are correct but a personal account has been entered where a business account was expected, or vice versa.
Why CoP Matters
CoP became even more important following changes to the UK’s APP fraud reimbursement regime in October 2024.
Eligible victims of Authorised Push Payment fraud can now receive reimbursement of losses up to £85,000 per claim, with the cost shared between the sending and receiving payment firms.
For businesses, this reinforces the need to take CoP warnings seriously. If a mismatch is deliberately overridden and a payment subsequently proves fraudulent, there is a clear record that the risk was identified before the payment was made.
The aim is not to prevent every payment that produces a warning, but to ensure that exceptions are deliberate, understood and auditable.
Businesses Are on Both Sides of the Check
As a payer
Every outgoing payment can potentially involve CoP, including supplier invoices, payroll, refunds and expenses.
The greatest risk often comes when existing supplier bank details are changed. A request to change the bank account of a supplier you have paid for years should always be treated cautiously, particularly if the request arrives by email.
CoP provides an important additional control, but it works best when it is built into the payment process rather than treated as an optional final check.
As a payee
The receiving side of CoP is often overlooked.
When a customer sets up a payment to your business, their bank may check the account name against the name they have entered. If your trading name, brand or commonly used business name differs from the name registered against your bank account, the customer may receive a warning.
Some customers will contact you. Others may simply postpone the payment or decide not to proceed. From your perspective, there may be no obvious failure — the payment simply never happens.
Businesses that trade under a brand name, have rebranded, use shortened names or collect payments through another legal entity should therefore check exactly what name their bank returns through CoP.
What CoP Does Not Do
CoP is an important fraud control, but it is not a guarantee that a payment is safe.
A successful match confirms that the name corresponds to the account. It does not confirm that the business is genuine, that an invoice is legitimate or that the amount is correct.
It also does not apply to Direct Debits, which operate differently from push payments.
For this reason, CoP should form part of a wider payment verification strategy alongside controls such as modulus and sort-code checking and, where appropriate, open banking verification.
Making CoP Part of the Process
A check that employees have to remember to perform is weaker than one built into the workflow.
Businesses should:
- Check at the right point: Verify new or amended bank details when they are entered, rather than waiting until the payment run.
- Define how warnings are handled: Establish who can stop a payment and what action is required for close matches or no matches.
- Keep an audit trail: Record the CoP result, who reviewed it and what decision was made.
- Plan for volume: Payrolls and large supplier runs should be capable of being checked in bulk or through an API rather than requiring hundreds of individual manual checks.
What Businesses Should Do Now
Businesses should start by checking the name their own bank returns through CoP and ensuring that their invoices, website and payment pages reflect it.
They should also make CoP a required part of the process whenever bank details are added or changed, independently verify supplier changes, establish clear procedures for dealing with warnings, and retain a record of both the check and the decision made.
Confirmation of Payee is one of the most practical controls available for reducing payment fraud. Its real value comes when it is embedded into the payment workflow — and when businesses remember that they are both making payments and receiving them.
SmarterPay builds account validation directly into the payment process. Its platform includes modulus and sort-code checking, open banking account verification for Direct Debit setup, and Confirmation of Payee through cloud workflows and APIs, supported by a full audit trail.
To discuss how these controls could fit into your payment processes, contact the SmarterPay team.